
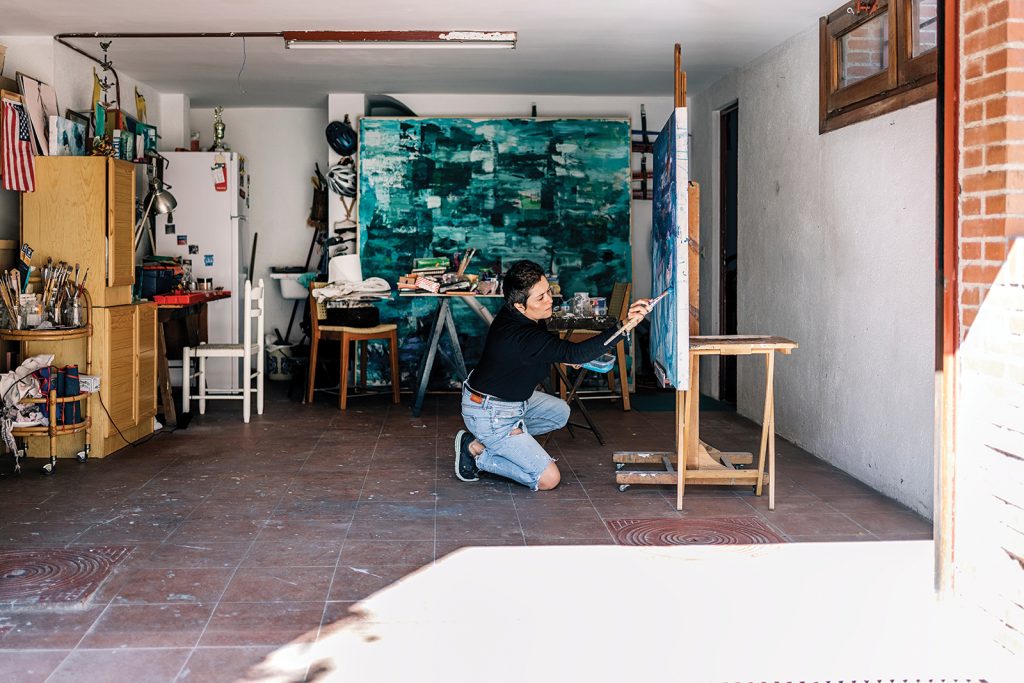
Are you a professional artist who creates your work at home? Your home studio might be your sanctuary for creativity, but have you considered how your artwork and equipment would be protected if disaster struck—such as a fire or tornado? While commercial insurance policies often cover inventory in storefronts or rented studio spaces, home-based artists need to pay special attention to the limitations and exclusions of their homeowners insurance policies.
Does Homeowners Insurance Cover Art Created at Home?
Many artists assume their homeowners policy automatically covers works they create and store at home. The reality is coverage depends on your individual policy and the nature of your art business. In some cases, you can add an incidental business endorsement to your homeowners insurance, which may cover business property used at home, but coverage is often limited and subject to eligibility requirements.
Limitations and Eligibility for Incidental Business Endorsements
Even with an incidental business endorsement, there are important limitations to consider—like the type of art you create and the tools you use—which can affect your eligibility and coverage. For example, painters may be able to insure their supplies and finished work, but artists who create pottery or glasswork with kilns or other high-heat furnaces may face exclusions. High-value or specialized equipment could also be subject to strict coverage limits, leaving you underinsured in case of a loss.
Another key factor is how you use your home studio. If clients regularly visit your home without appointments to view or purchase your art, your home may be considered a storefront. In such cases, an incidental business endorsement likely will not apply due to increased liability risks. If a customer were injured while shopping in your home, your homeowners policy might not provide liability coverage. In these situations, a commercial policy or general liability policy is usually a more appropriate choice.
Coverage for Art Shows and Exhibits
It’s also important to note that homeowners policies—with or without a business endorsement—typically do not extend coverage to off-premises events, such as art shows or gallery exhibits. Additionally, if you host large gatherings at your home to showcase your art, you may be ineligible for an endorsement due to the increased risk of accidents and liability claims.
Assigning Value and Understanding Coverage Limits
Artists often view their creations as priceless, but when it comes to insurance, you must assign a fair market value to your work. Under the incidental business endorsement, coverage for merchandise is usually capped at $5,000 or less. This limit may fall far short of your needs if your inventory or equipment is more valuable. If you require more coverage, a separate commercial policy may be necessary as the incidental business endorsement alone will not be enough.
As always, getting appropriate coverage for your art and your business means reviewing your insurance options carefully. Don’t assume your homeowners policy provides all the coverage you need. Discuss your unique situation with an insurance professional who understands the needs of artists. Be clear about the nature of your work, the equipment you use and how you interact with clients. By taking the time to secure appropriate coverage, you can focus on creating art with confidence.
This article provides general information about insurance topics and may not reflect the terms of any particular policy. Coverage depends on the policy as issued, including applicable terms, conditions, limitations, and exclusions. For advice about your situation, consult a licensed insurance professional.


